
- 7 U.S. Cities Where Summers Have Gotten Measurably Hotter Since 1990 - September 16, 2026
- I’ve Studied Climate for 10 Years – These 6 Warning Signs Instantly Worry Me - September 16, 2026
- As Plastic Bags Slowly Disappear From Stores, Here’s What to Do With the Reusable Ones You’ve Saved - September 16, 2026
1. Miami, Florida
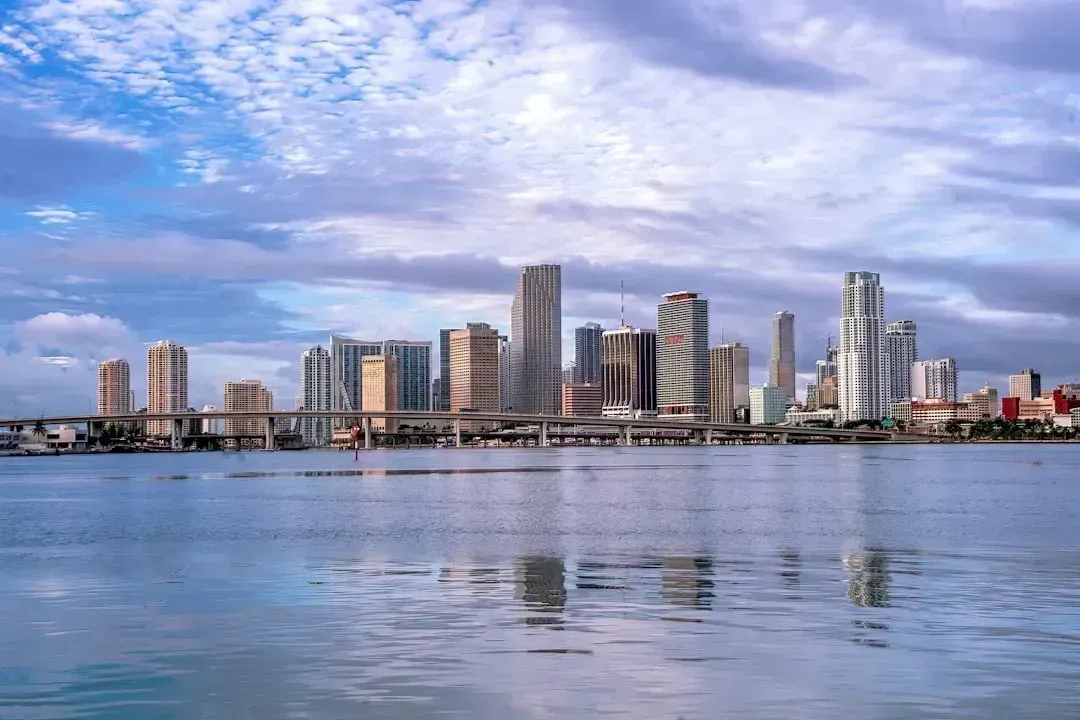
Miami sits at the top of nearly every list of cities facing runaway insurance costs, and flood coverage is a big part of that story. An analysis found that Miami will see the greatest increase in insurance premiums over the next 30 years, skyrocketing 322% from current levels due to rising hurricane risk. That figure covers overall insurance, but flood exposure is a major driver given the city’s low elevation and porous limestone bedrock.
Local agents and national trackers both flag Miami as a hot zone for flood premium growth. Miami is among the U.S. locations seeing the fastest growing flood insurance costs, alongside New Orleans, Houston, and Charleston. With FEMA’s Risk Rating 2.0 now fully phased in, homes previously underpriced relative to their actual flood exposure are being pushed toward their true cost year by year.
2. New Orleans, Louisiana
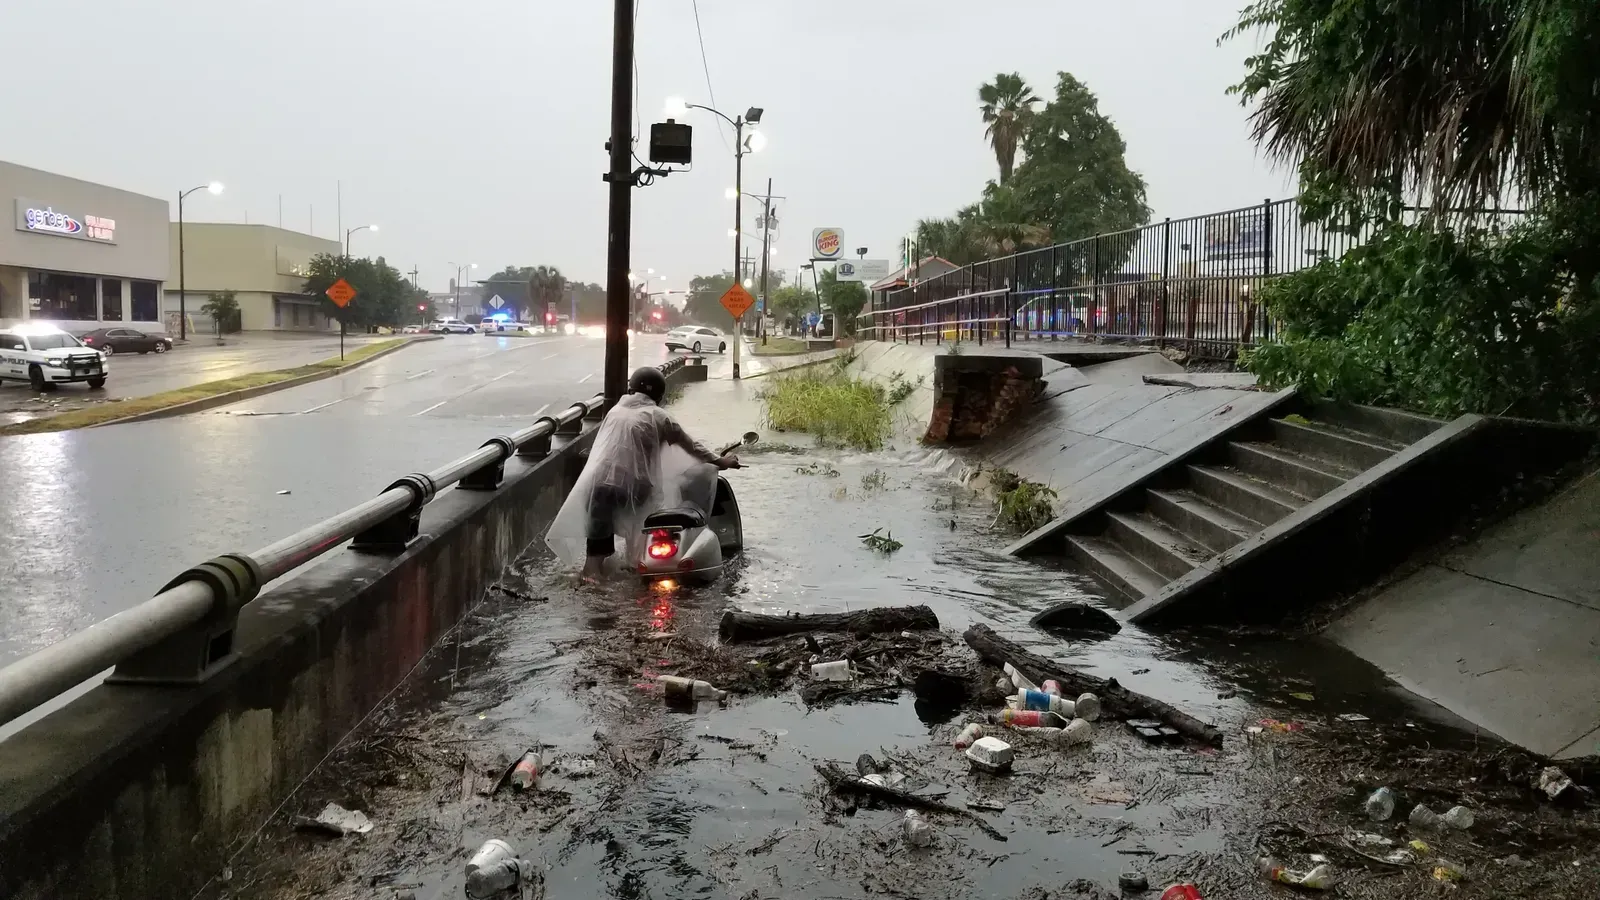
No city on this list faces a starker long term projection than New Orleans. Nationally, flood damages are estimated to increase by an average of 28% by 2055, with New Orleans predicted to see a staggering 533% increase, the worst of any metro studied. That number reflects projected flood damages rather than a locked in premium hike, but insurers ultimately price toward expected losses.
The city is already living through the early stages of this shift. About 80% of NFIP policyholders in Louisiana saw their premiums increase under the new pricing model, and in parishes like Jefferson and Orleans, average NFIP rates roughly doubled. The result has been a wave of homeowners dropping coverage entirely, which only raises the stakes for those who stay insured. More than 52,000 Louisiana residents dropped their NFIP policies, unable or unwilling to absorb the higher cost, leaving them uninsured against flooding in one of the most flood-prone states in the country.
3. Houston, Texas
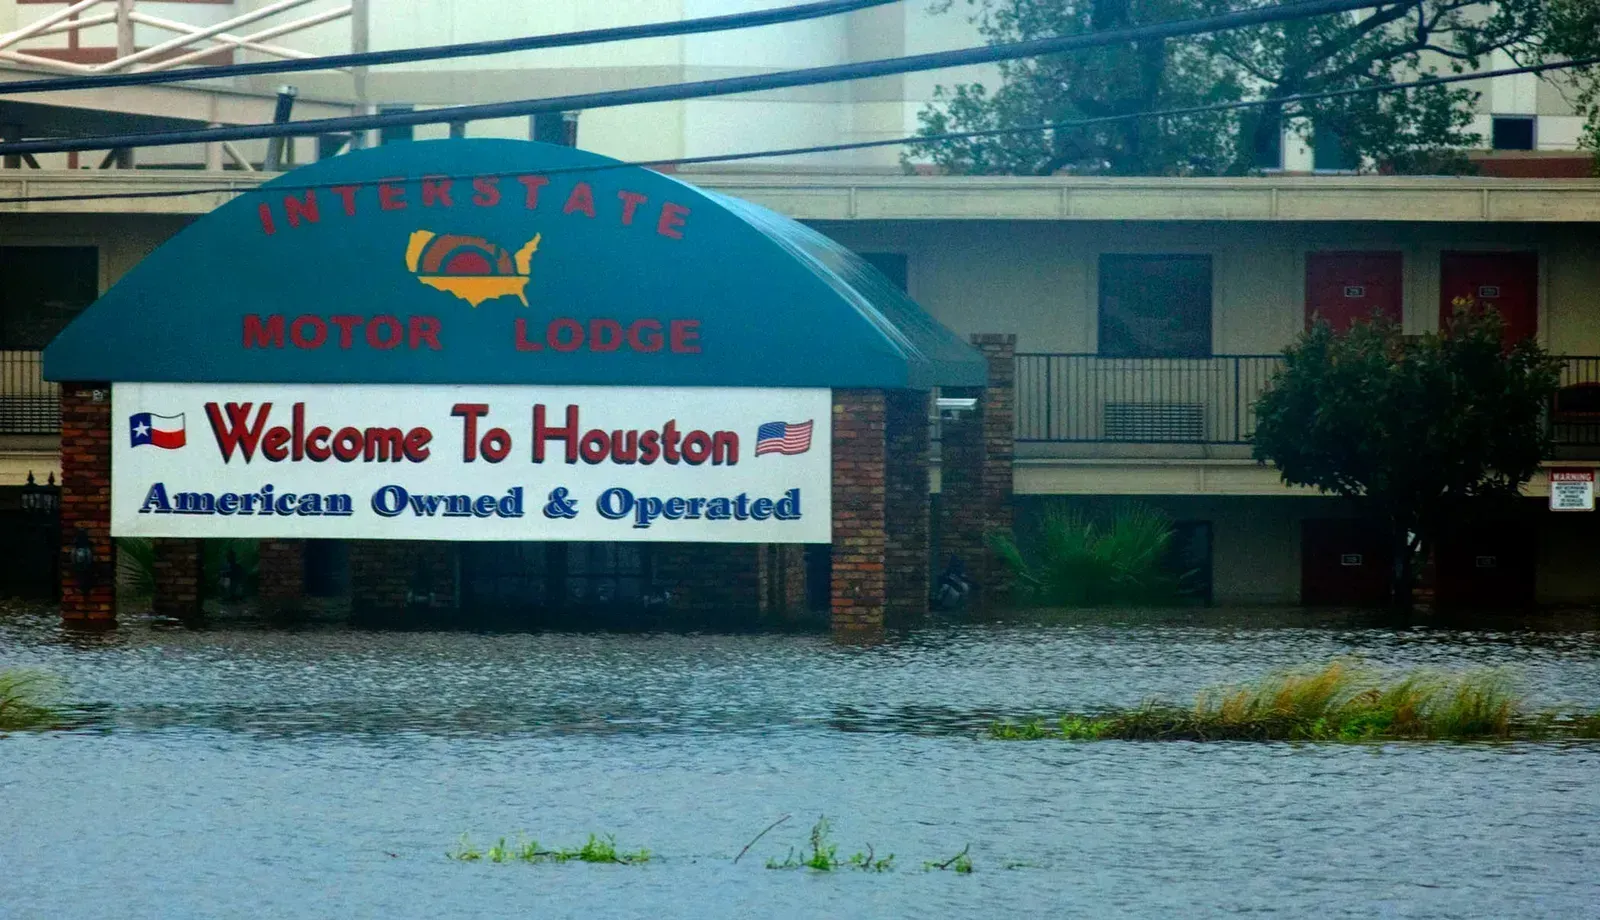
Houston’s flood risk isn’t new, but the way it’s being priced is. Homeowners across Harris County have been opening renewal notices and finding repeat double digit jumps. Homeowners in Harris County who recently opened their FEMA renewal letter have felt a sudden wave of financial stress, with many seeing repeat increases often up to 18 percent.
The mechanism behind this is what industry blogs call the glide path, a federally mandated schedule that keeps nudging premiums upward each year. Many Houston homeowners are on the Glide Path, a federally mandated rate increase schedule, because under Risk Rating 2.0 every home has a true risk premium, and if a homeowner is paying less than that number, FEMA is required by law to raise the rate by up to 18 percent each year until it’s reached. For a metro area with sprawling floodplains and heavy annual rainfall, that glide path has years left to run before many properties catch up to their full risk cost.
4. Jacksonville, Florida
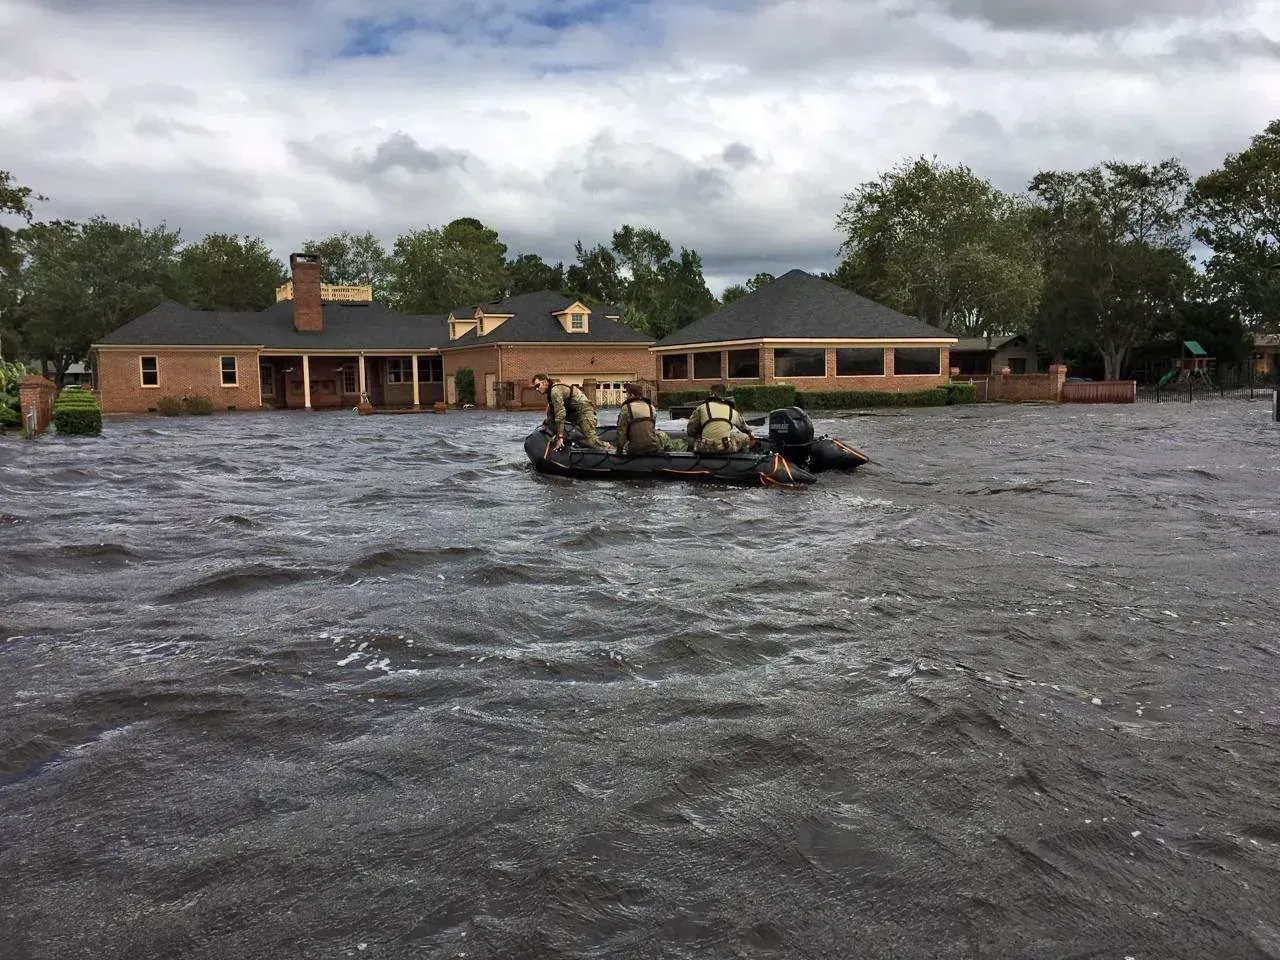
Jacksonville doesn’t always get the same attention as Miami or Tampa, but the numbers tell a similar story. Storm risk is projected to cause huge insurance premium jumps for Jacksonville, at 226% over the next 30 years. That places it second only to Miami among the major metros studied.
Jacksonville’s flood exposure comes from a mix of river flooding along the St. Johns and coastal storm surge, a combination that makes pricing especially complicated under FEMA’s newer, more granular methodology. As replacement costs rise and the agency continues weighing distance to water and elevation more heavily, homeowners in flood prone pockets of the city are likely to see premiums climb steadily rather than level off anytime soon.
5. Tampa, Florida
Tampa Bay’s combination of low lying neighborhoods and a coastline exposed to storm surge has made it one of the more closely watched markets for insurers. Tampa is projected to see a 213% jump in insurance premiums over the next three decades, driven largely by storm risk. That kind of trajectory puts real pressure on affordability for a metro that has also seen strong population growth in recent years.
What makes Tampa notable is how much of its flood exposure sits outside the traditional high risk zones on FEMA’s older maps. As the agency’s newer approach folds in more granular data about drainage, ground elevation, and storm surge modeling, more Tampa area homes are being reclassified with premiums that better reflect actual risk, and for many, that means paying considerably more than they did just a few years ago.
6. Charleston, South Carolina
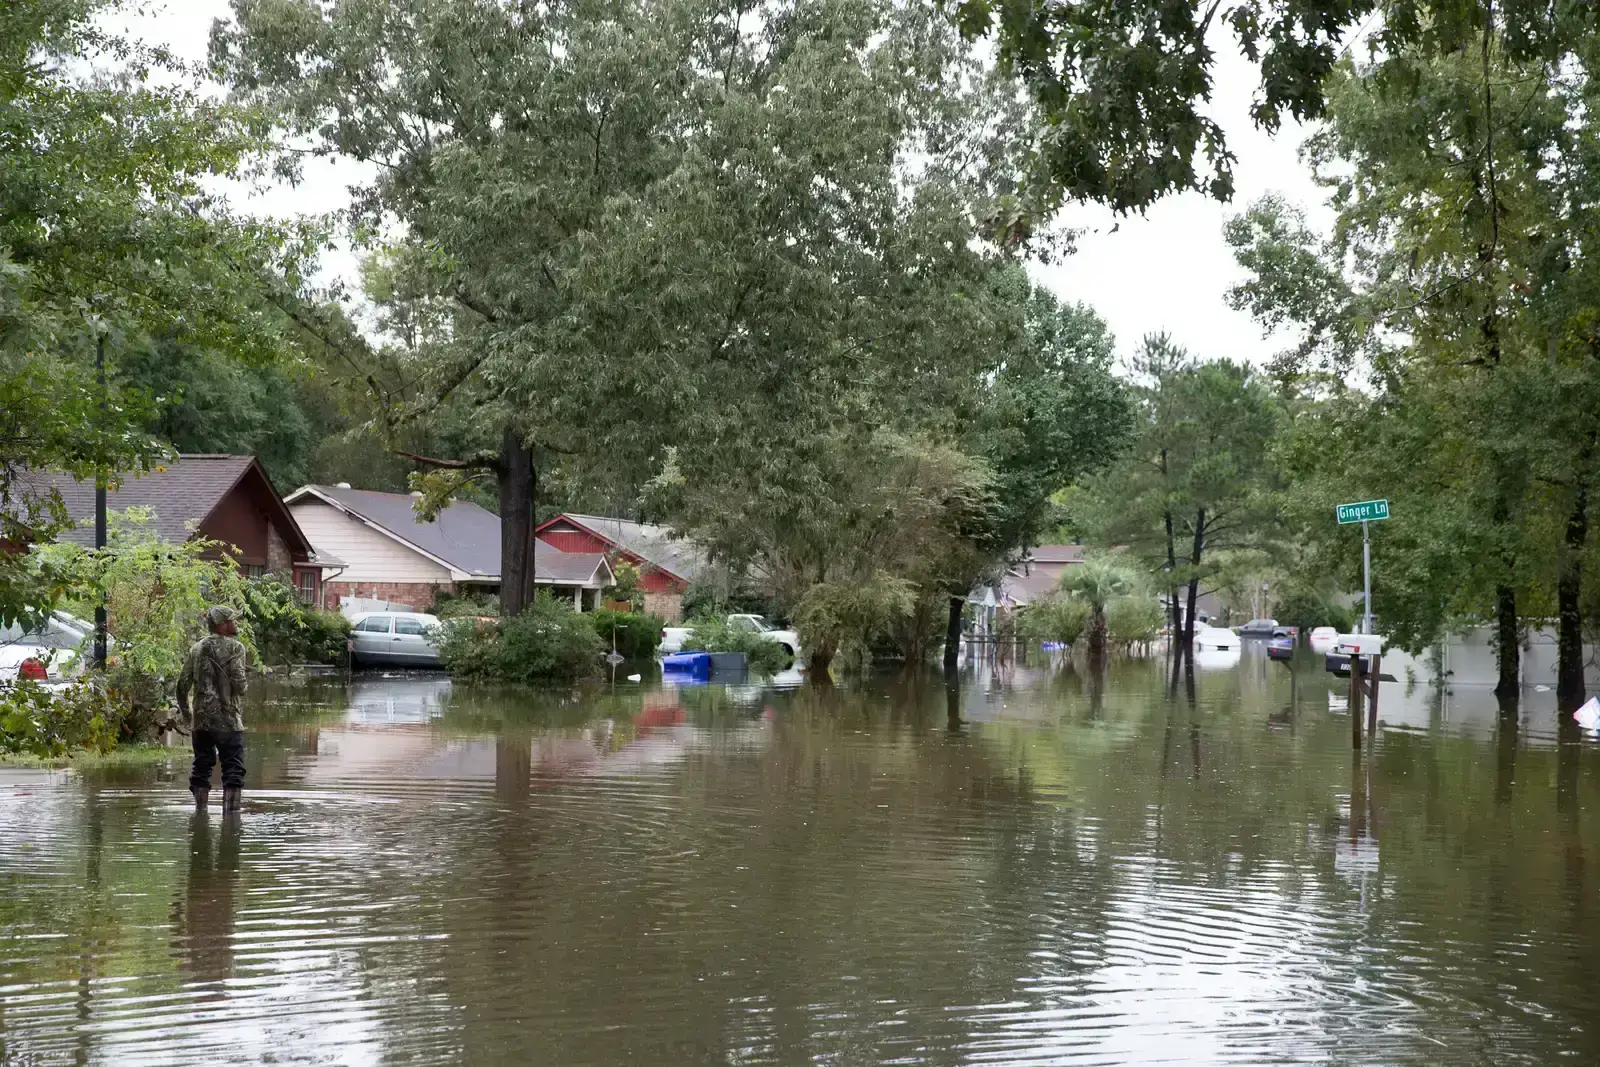
Charleston’s historic downtown and its low country geography make it one of the most flood vulnerable cities on the Atlantic coast. It shows up repeatedly in industry tracking of markets with the fastest growing flood insurance costs. Charleston is named among the U.S. hot zones seeing the fastest-growing flood insurance costs, alongside New Orleans, Houston, and Miami.
Sea level rise compounds the challenge here in a way that’s different from inland flood risk. Charleston already experiences regular nuisance flooding during high tides, and as that baseline water level creeps up, insurers are factoring in a slower but steadier form of risk that doesn’t require a hurricane to cause damage. Charleston is listed among locations where flood insurance cost per year can range from $800 to over $5,000 depending on proximity to the water, and those numbers are likely to trend upward as sea levels rise and drainage systems age.
7. Atlantic City, New Jersey
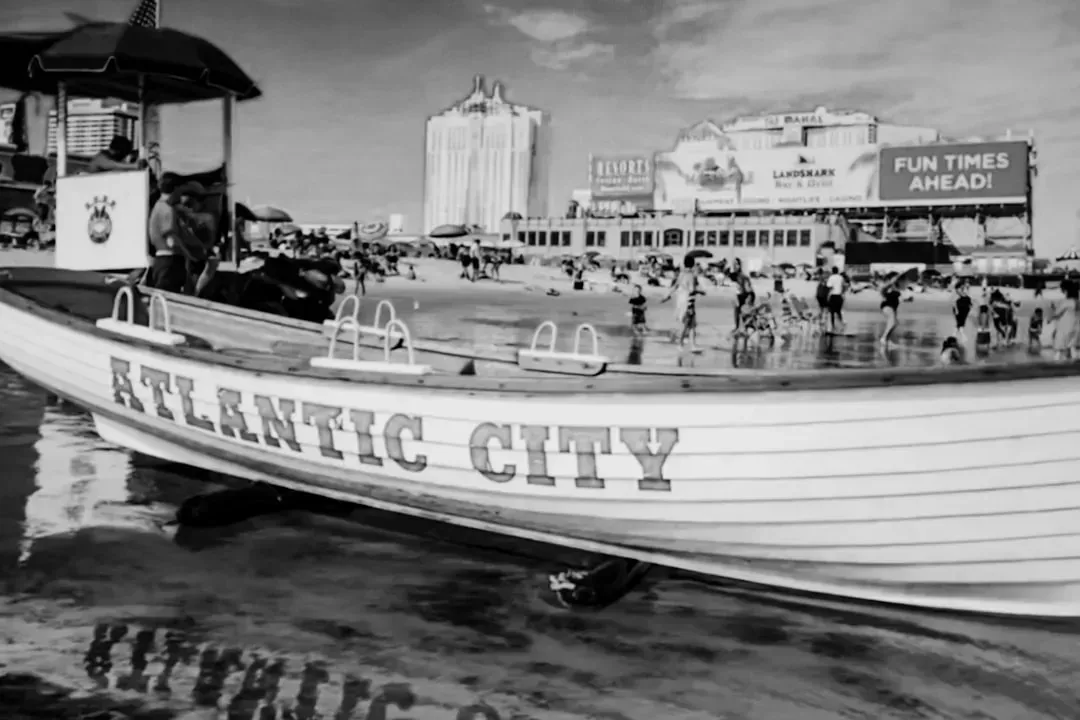
Atlantic City rounds out this list with one of the sharpest long term flood damage projections in the country. Atlantic City is predicted to see flood damages increase by 296% by 2055, ranking among the worst hit metros nationally. That kind of projection tends to show up in premiums well before the damage itself occurs, since insurers price against expected future losses rather than waiting for them to materialize.
The city’s barrier island geography leaves it particularly exposed to both coastal storm surge and rising sea levels, a combination that has already reshaped how FEMA and private insurers view individual properties there. Homeowners further inland but still within flood zones tied to back bays and tidal marshes have not been spared either, since the newer pricing approach looks at proximity to any water source rather than just oceanfront exposure.
Every one of these cities shares a common thread: aging pricing models built decades ago are being replaced by systems that price flood risk property by property, and the properties that were quietly underpriced for years are the ones absorbing the steepest increases now. Because federal law caps most annual hikes at eighteen percent, many homeowners in these areas won’t feel the full weight of their new true risk rate all at once. Instead, it will arrive in installments, one renewal notice at a time, for years to come.