
California: rewriting the rules after the wildfires
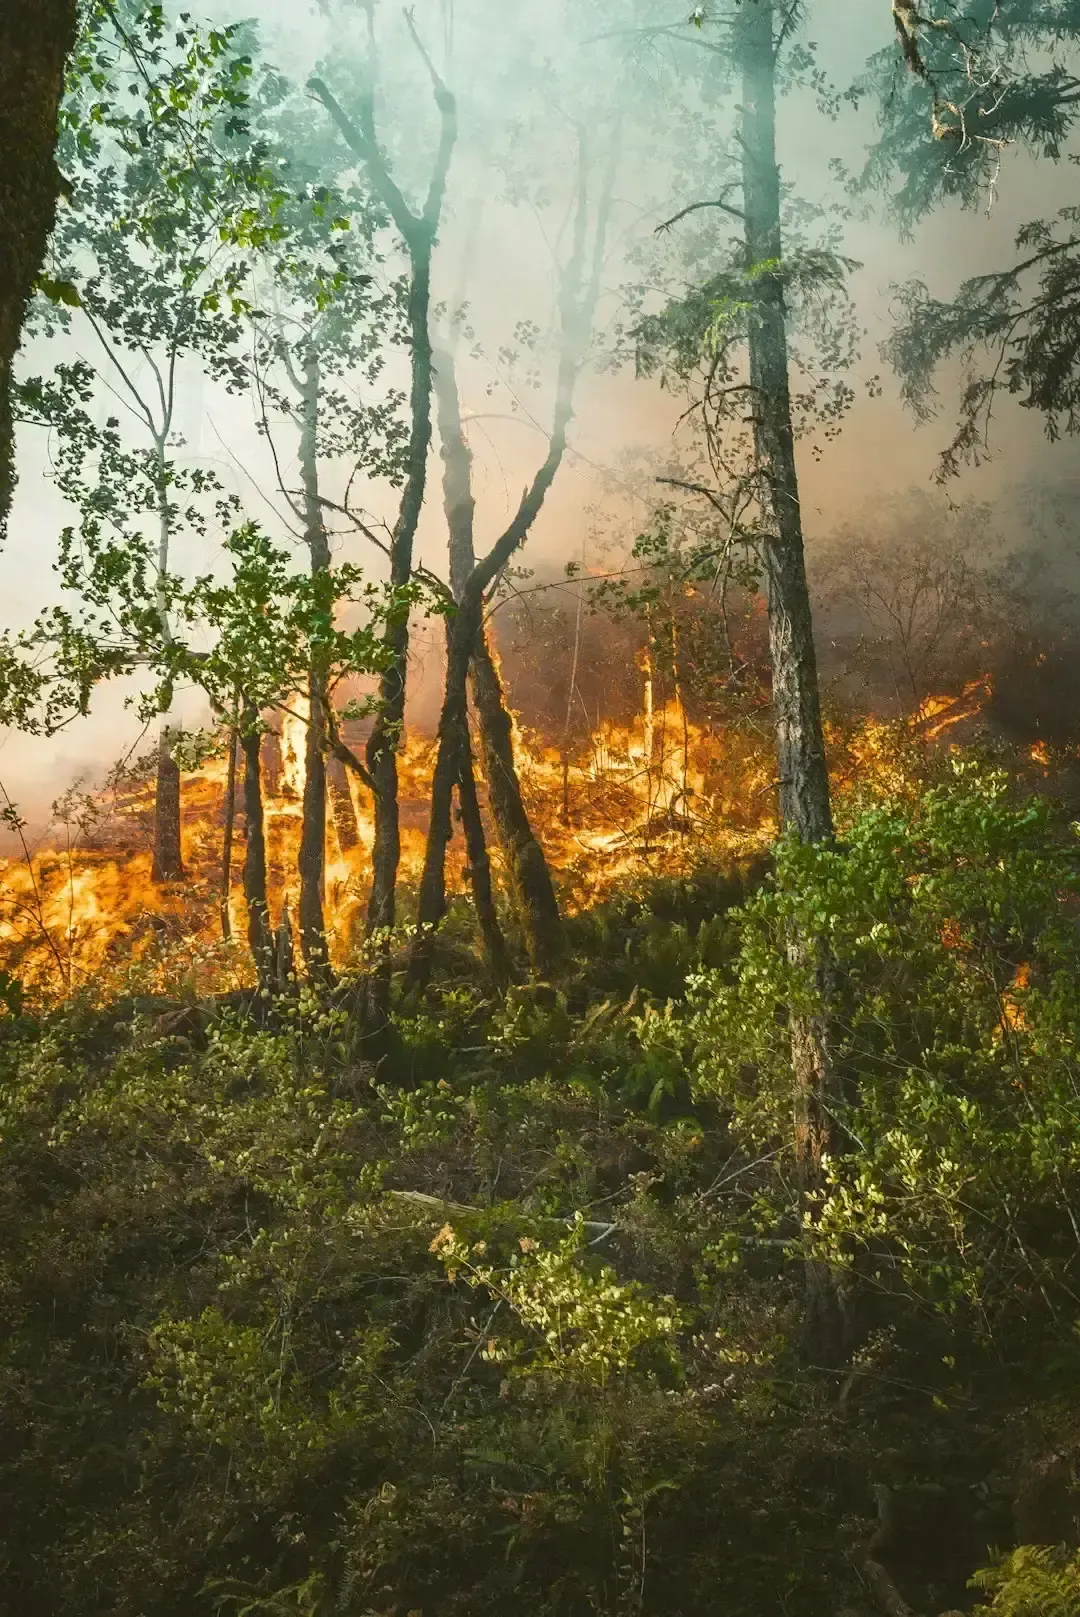
California’s insurance market has been under strain for years, and the January 2025 Los Angeles wildfires accelerated a reform process that was already underway. Many private insurers had withdrawn from certain exposures as climate change intensified wildfire risk, leaving gaps that the state’s FAIR Plan had to fill, though the 2025 fires exposed how fragile that safety net really was. Insurance Commissioner Ricardo Lara’s Sustainable Insurance Strategy is the umbrella under which most of the state’s changes now fall.
Under that strategy, insurers using Department-reviewed wildfire catastrophe models are now required to provide and maintain coverage in wildfire-prone areas, a shift meant to help policyholders transition out of the FAIR Plan. A new public model is also in the works. The California Wildfire Public Model Act, known as SB 429, supports the nation’s first publicly available wildfire loss catastrophe model, giving homeowners and policymakers a transparent point of comparison against the private models insurers use. Separately, new 2026 laws require residential replacement cost policies to include building code upgrade coverage of at least 10% of the dwelling limit, and a related law will eventually bar insurers from refusing coverage to homes that meet the state’s fire hardening and defensible space standards.
Florida: turning down the litigation temperature
Florida spent years as the undisputed capital of homeowners insurance lawsuits, and its 2022 and 2023 reforms were designed to change that. They appear to be working. The state’s share of nationwide homeowners insurance lawsuits dropped from 79% in 2020 to 41% in 2025, while its share of national homeowners claims fell from roughly 9% to under 5% over the same period.
The practical effect has been more competition and lower rates. Twenty-one new companies have been approved to write residential property policies in Florida since the reforms took effect. Meanwhile, Citizens Property Insurance Corporation policyholders began seeing premium decreases in spring 2026, with statewide rates going down by an average of 8.7% and more than 150,000 policyholders receiving reductions of 10% or more. Florida’s domestic property insurers posted a pooled combined ratio of 83% in 2025, the lowest in more than a decade, a sign the market has become genuinely profitable again.
Louisiana: forcing more transparency at renewal
Louisiana has taken a lighter touch than Florida, focusing less on the courts and more on what homeowners actually see on their bills. Under a new state law effective January 1, 2026, Louisiana insurers must prominently display the prior premium alongside the new premium offered at renewal. That sounds like a small thing, but it removes one of the more common consumer complaints, the feeling that a rate hike arrives with no context.
The state has also tightened its own rate filing standards. The law now states that rate filings must not be “excessive, inadequate or unfairly discriminatory.” On top of that, Louisiana is tightening notice requirements for home and auto insurance cancellations by doubling the notice period insurers must give. Louisiana’s push mirrors what’s happening in the Southeast more broadly, where lawmakers have watched Florida’s approach and borrowed pieces of it for their own markets.
Texas: shining a light on nonrenewals
Texas homeowners have long complained about getting dropped or denied with little explanation, and the state legislature responded with a transparency mandate. A new Texas law effective January 1, 2026 now requires insurers to provide written reasons when declining, cancelling, or nonrenewing a home or auto insurance policy. That alone is a meaningful shift for a state where the reasons behind coverage decisions were often opaque.
The law goes further by building a public data trail. It also mandates quarterly reporting to the Texas Department of Insurance of these cancellation and nonrenewal reasons, organized by ZIP code. The Texas Department of Insurance will then make this data public, a move intended to increase transparency and give homeowners clearer information about insurer decisions. Regulators expect the ZIP code breakdown to reveal patterns, whether certain neighborhoods are being systematically dropped, that individual complaints alone never could.
Colorado: putting wildfire scores in homeowners’ hands
Colorado’s home insurance market has been under pressure from both wildfire and hail, and its newest law addresses the wildfire side head on. Colorado House Bill 25-1182, signed into law on May 28, 2025, is described as the most significant change to wildfire insurance regulation in the state in decades. It takes effect midway through 2026.
Starting then, any insurer using a wildfire risk model, catastrophe model, or scoring method to underwrite, price, non-renew, or surcharge a homeowners policy will be legally required to share that information with the policyholder, and to factor in the mitigation work homeowners have actually completed. That last part matters because, as state lawmakers have pointed out, Coloradans had invested in wildfire mitigation on their properties only to receive no discounts from their insurers. The state has also leaned into hail mitigation grants, since the Division of Insurance found hail damage accounts for between 26% and 54% of an annual homeowners premium, with mitigation potentially saving homeowners between $82 and $387 a year.
North Carolina: a commissioner pushing back on rate bureau demands
North Carolina runs its home insurance rates through an unusual system involving a Rate Bureau that represents insurers, separate from the Department of Insurance itself. That structure came under intense scrutiny after the Bureau filed for a massive increase. The N.C. Rate Bureau originally requested an average 42.2% increase, with proposed increases of up to 99.4% in some areas, in a filing submitted in January 2024.
Commissioner Mike Causey rejected that request outright and negotiated it down substantially. The agreement ultimately signed increased the average statewide base rate by 7.5% on June 1, 2025, and another 7.5% on June 1, 2026. The deal also caps rate increases at 35% for any specific territory and prevents the Rate Bureau from submitting another increase request until June 2027. A similar standoff played out again in late 2025, when the Rate Bureau filed for a combined 68.3% dwelling insurance increase over two years. That filing was ultimately settled at a 5% increase scheduled to take effect on October 1, 2026, followed by another 5% the following year.
Georgia: betting on tort reform to cool premiums
Georgia has followed Florida’s lead, wagering that limiting lawsuits will do more for insurance costs than direct rate regulation. Governor Brian Kemp’s pitch has been straightforward: putting limits on lawsuits will halt rising insurance costs. Georgia joined a small group of states pursuing this path in the past year, with industry watchers in Florida specifically noting the trend.
Florida’s own reform advocates have pointed to Georgia and Louisiana as states that have taken a page from Florida’s playbook and passed their own legal system abuse reforms in the last year. Independent researchers are more cautious about how much homeowners will actually benefit. The reality is more complicated than the simple pitch suggests, since changes could reduce liability costs for businesses and commercial property owners, while the evidence is mixed on whether it drives large premium reductions for home and auto policies, and some researchers argue tort reform mainly fattens insurer profits rather than cutting prices. That tension, cheaper lawsuits versus cheaper premiums, is likely to define how Georgia’s experiment is judged over the next couple of years.
Oklahoma: an election that could reshape rate authority
Oklahoma’s home insurance market has been squeezed hard by severe weather, and premiums have climbed accordingly. Since 2023, Oklahoma’s average home insurance premiums have increased by 31%, according to Insurify data. That kind of jump has turned the state’s insurance commissioner race into a genuine policy fight rather than a down ballot afterthought.
Part of the reason is a new power tied to the office itself. The next elected commissioner will be the first to exercise a new authority to reject excessive rate increases. Analysts tracking the 2026 midterms have flagged Oklahoma alongside California and Georgia as states where policyholders are most likely to feel the direct influence of a new insurance commissioner on their home insurance premiums. Given the state’s exposure to tornadoes and hail, whoever wins that seat will have real leverage over how aggressively insurers can raise rates going forward.
What ties these eight states together
None of these states arrived at reform for identical reasons, but the pattern is hard to miss. Climate-driven disaster losses, whether wildfire in California and Colorado, hurricanes in Florida and Louisiana, or hail and tornadoes in Texas and Oklahoma, are forcing regulators to intervene more directly than they have in decades. At the same time, litigation costs in Florida, Georgia, and Louisiana show how legal environments can be just as influential on premiums as weather itself.
The common thread across nearly every reform is transparency. Texas wants written reasons for nonrenewals. Colorado wants wildfire scores made visible. Louisiana wants prior premiums shown at renewal. North Carolina and Florida are both, in different ways, trying to make the negotiation between insurers and regulators less opaque to the public footing the bill. Whether these measures translate into meaningfully lower premiums will depend heavily on how the next few hurricane and wildfire seasons play out, but the regulatory groundwork being laid now is likely to shape home insurance in these states for years to come.

- My Mom Listed 8 Sustainable Habits From the ’70s – How Many Do You Still Practice? - September 16, 2026
- 7 Mountain Ranges Where Snowfall Has Measurably Decreased This Decade - September 15, 2026
- The Top 13 Animal Species That Consistently Live the Longest Lives - September 15, 2026
