
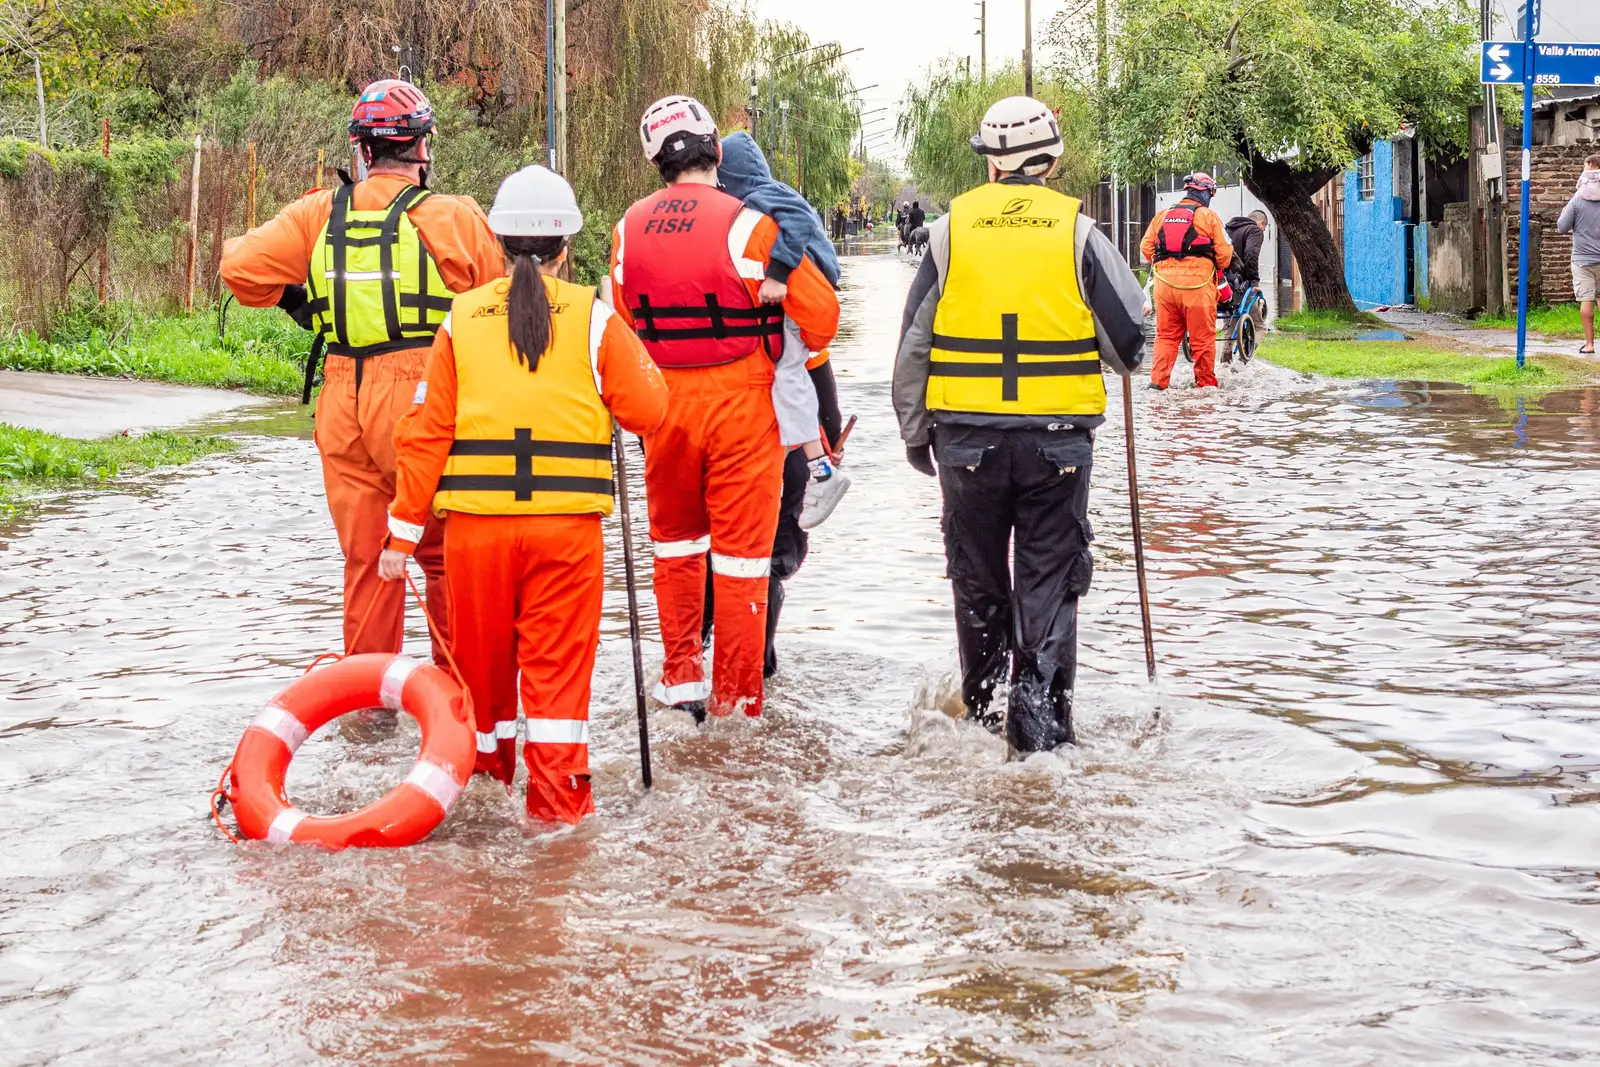
Myth 1: Your homeowners insurance already covers flood damage
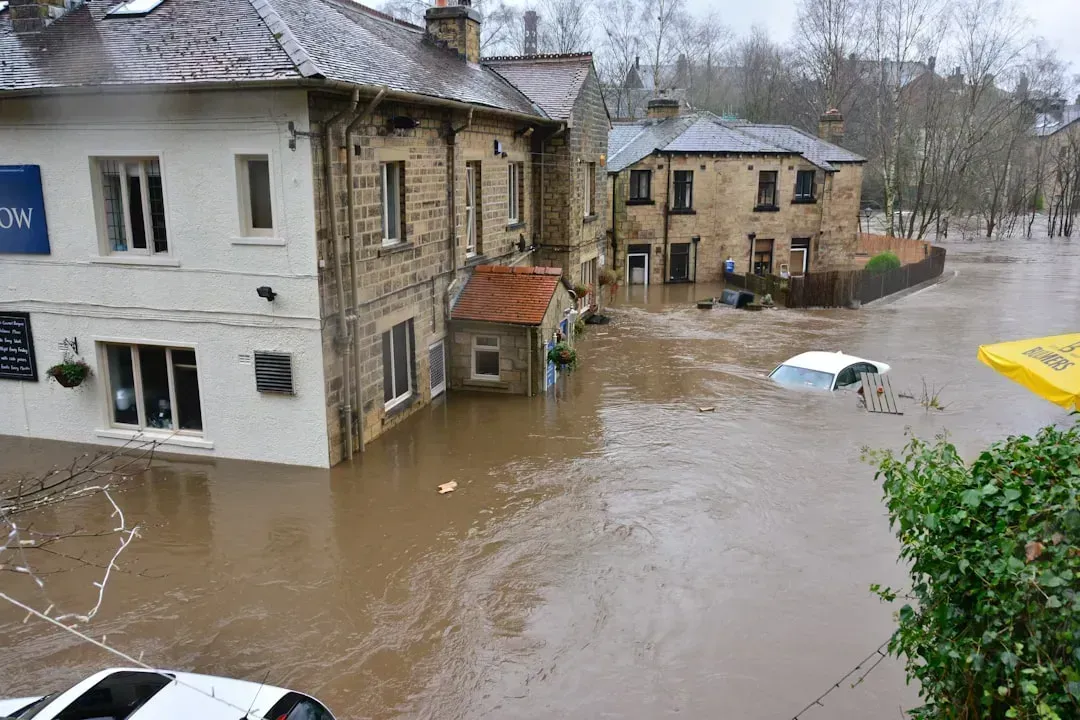
This is probably the most expensive misunderstanding in American home insurance. A standard homeowners policy is built to handle fire, wind, theft, and a handful of water-related accidents like a burst pipe, but it draws a hard line at flooding. Homeowners’ insurance does not cover flood damage, and federal flood insurance, purchased through your insurance agent or company, is the only guaranteed flood insurance available for your home.
Many homeowners only discover this gap when they’re standing in a ruined living room with an adjuster telling them the claim is being denied. Despite common belief that homeowner’s insurance policies cover flooding, many homeowners do not find out until it is too late that their homeowners’ policies do not cover flooding. Flood coverage has to be purchased as a separate policy, whether through the NFIP or a private insurer, and it typically comes with a waiting period before it kicks in.
Myth 2: If you’re outside the flood zone, you’re outside the risk
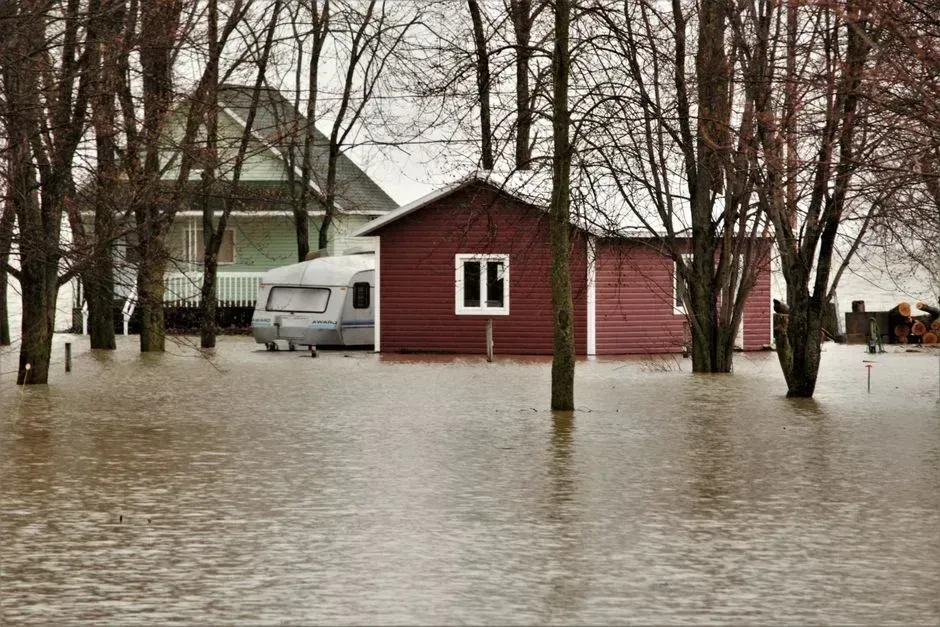
Flood maps are useful, but they’re not a guarantee. They estimate probability, not certainty, and a huge share of flood damage happens to people who thought they’d checked that box already. Many people believe that if they live outside the floodplain, they don’t need to buy flood insurance, but almost one third of all flood claims are paid on structures outside identified floodplains.
Heavy rainfall, overwhelmed storm drains, and failed infrastructure don’t check a map before they flood a basement. Floods can occur anywhere, and an area near a levee or a dam is at risk of the levee or dam breaking. That’s part of why FEMA’s newer pricing model looks at rainfall-driven flooding specifically, rather than relying only on zone lines. Risk Rating 2.0 also adds pluvial flood risk, or flooding from heavy rainfall, which reflects just how common flooding outside mapped zones has become.
Myth 3: Federal disaster aid will make you whole again
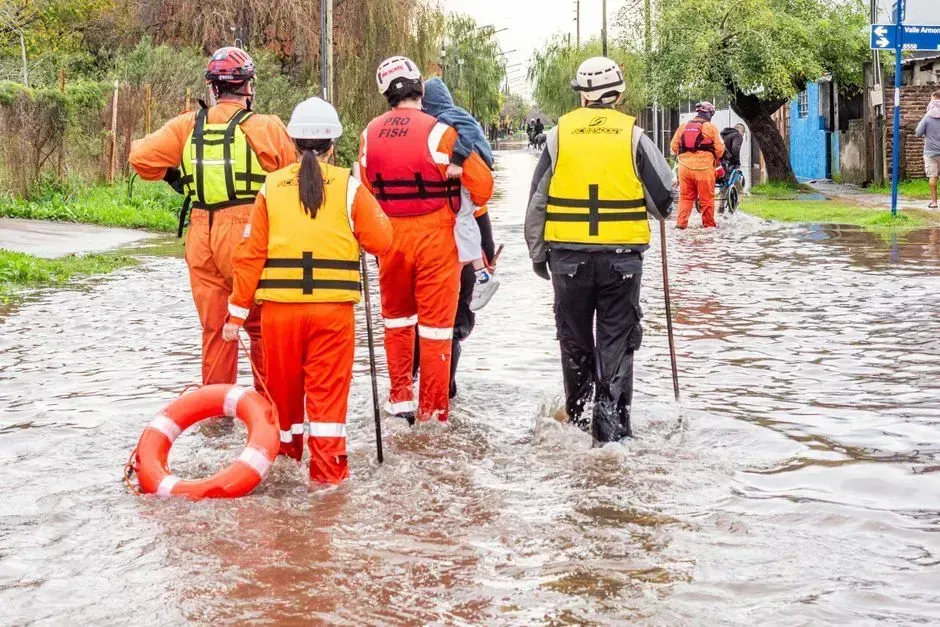
It’s tempting to assume that if a flood is bad enough to make the news, the government will step in and cover the damage. That assumption skips over two important details: aid isn’t automatic, and it usually isn’t free. Federal Emergency Management Agency disaster aid is only available during presidentially declared disasters, and federal aid is often in the form of a loan from the Small Business Administration that you must pay back with interest.
Even when a disaster declaration does come through, it’s far from guaranteed. Before a community is eligible for disaster assistance, it must be declared a federal disaster area, and a federal disaster is declared in less than 50% of flooding incidents. Flood insurance, by contrast, pays out regardless of whether the president ever signs a declaration.
Myth 4: A past flood or a high-risk address locks you out of coverage
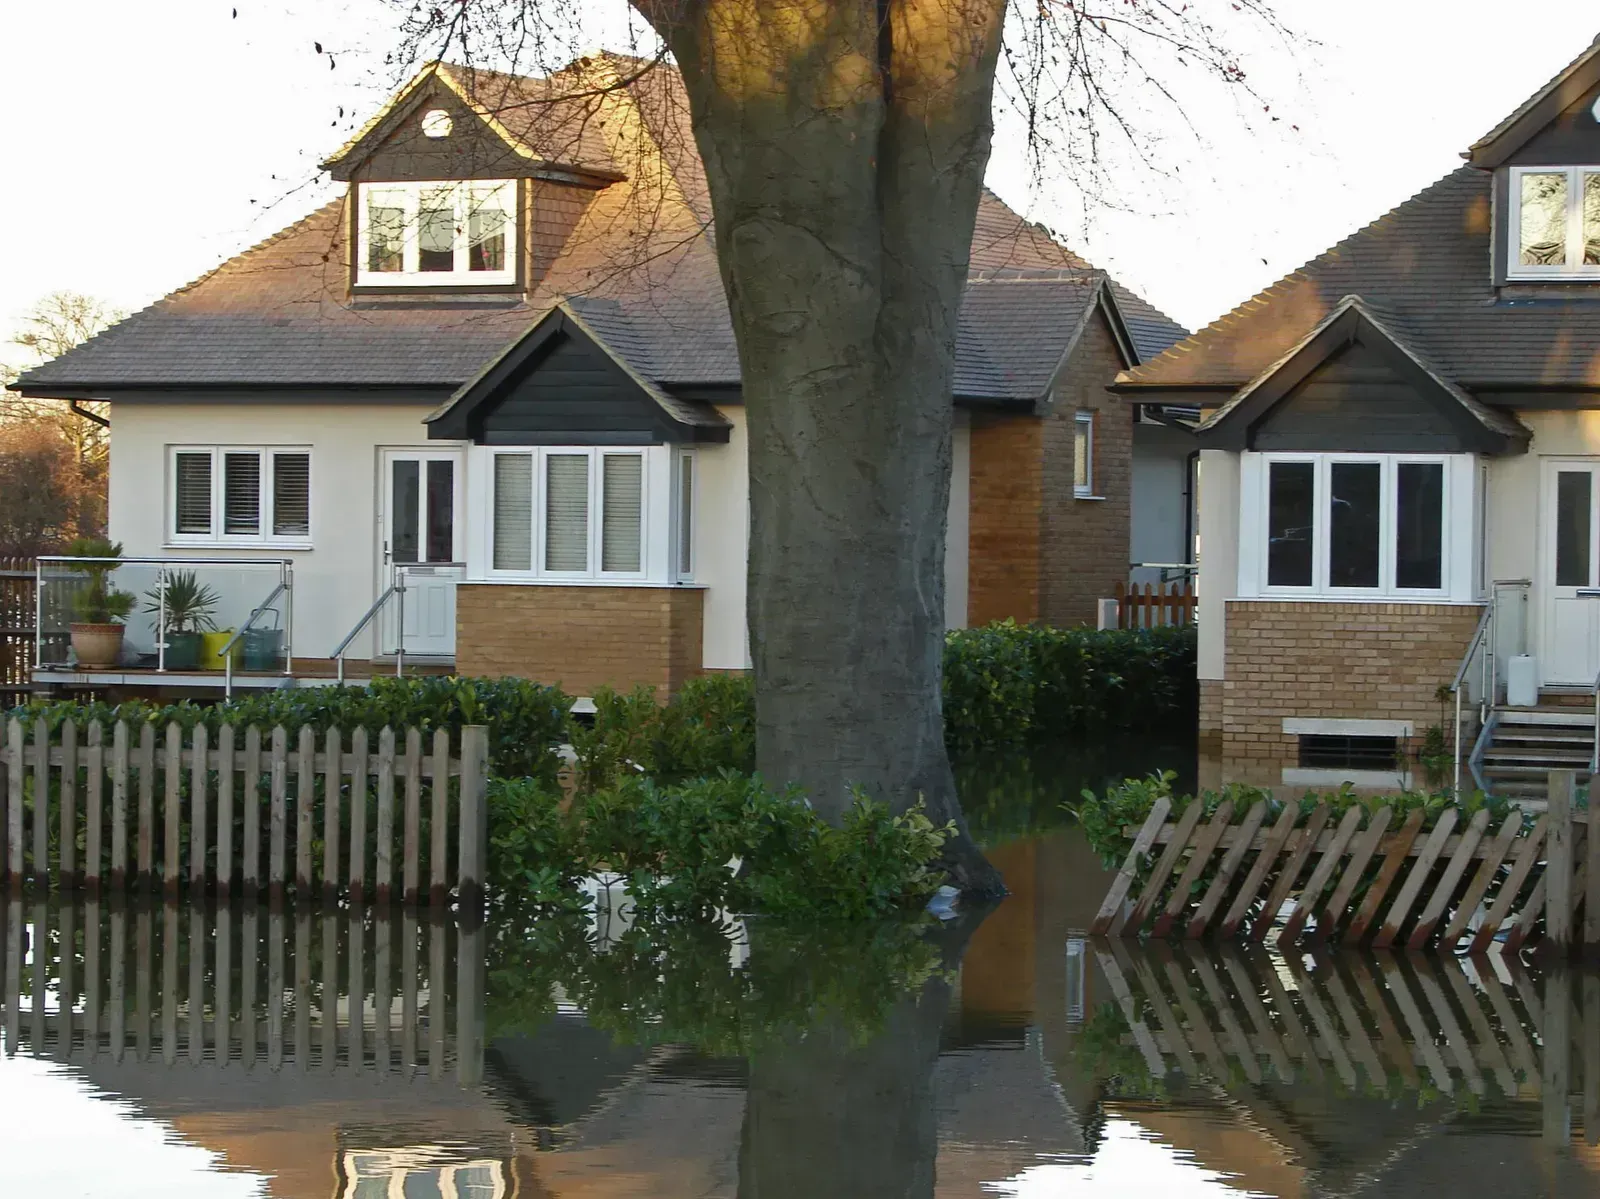
Some homeowners assume that once their house has flooded, or once they learn they’re in a high-risk zone, insurers simply won’t touch them again. That’s not how the NFIP works. Even if a home has been flooded previously, it doesn’t matter where you live or if your home has been flooded before, you may still buy flood insurance.
The same logic applies to location. Contrary to the belief that you can’t buy flood insurance if you are located in a high-risk area, you can buy federal flood insurance no matter where you live if your community belongs to the NFIP, except in Coastal Barrier Resources System areas. Repeated flooding can push premiums higher over time, but it doesn’t shut the door on coverage entirely.
Myth 5: Flood insurance won’t touch your basement
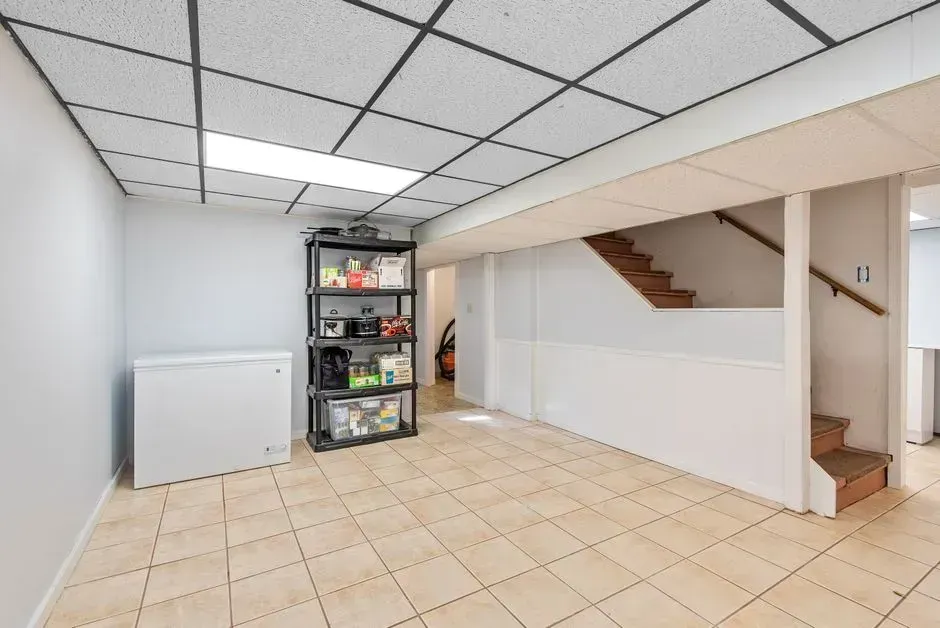
Basements have a reputation as the one part of the house flood insurance ignores completely. That reputation is out of date. Despite the myth that the NFIP does not offer any type of coverage for basements, the fact is yes it does, and the NFIP defines a basement as any area of a building with a floor that is below ground level on all sides.
The coverage isn’t unlimited, though, and it’s worth understanding the boundaries. Basement coverage under an NFIP policy includes clean-up expenses and repair or replacement of items used to service homes and buildings, such as elevators, furnaces, water heaters, air conditioners, utility connections, circuit breaker boxes, and pumps, but flood insurance will not cover the contents of a finished basement and basement improvements such as finished walls, floors, and ceilings. So a flooded mechanical system is covered, but that finished home theater in the basement is on its own.
Myth 6: Everyone’s premium is skyrocketing under the new pricing system
Since FEMA finished rolling out its Risk Rating 2.0 pricing model, a narrative has taken hold that every policyholder is getting hit with painful increases. The actual numbers tell a more mixed story. Some premiums will go up, some will go down, and some will stay about the same, and under Risk Rating 2.0, roughly two-thirds of policyholders with older pre-Flood Insurance Rate Map homes will see their premiums decrease.
For the households whose costs are rising, the increases are gradual rather than sudden. Policyholders who have premium increases will see their rates transition gradually, with most annual increases capped at 18%, and premiums will only increase until the full-risk rate is reached. That said, affordability pressure is real for some communities, and a 2025 academic paper found that premium increases associated with the NFIP’s new pricing system have substantially reduced NFIP policy uptake, with particularly large declines in lower-income communities. It’s also worth watching Washington closely, since on Feb. 3, 2026, the president signed legislation that extends the NFIP’s authorization to Sept. 30, 2026, and Congress must reauthorize the program again by that deadline to keep new policies flowing without interruption.

- The Shoreline Sucked Dry in Seconds – 5 Tsunami Signals Beachgoers Mistake for Low Tide - November 14, 2026
- 9 Dark-Sky Destinations Around the World Where the Stars Look Unreal - November 14, 2026
- The Fault Line That Never Slips – 7 Locked Seismic Zones Overdue for a Massive Release - November 14, 2026
