- Phantom Energy Sucking Power 24/7 – 7 Home Electronics Quietly Inflating Utility Bills - November 14, 2026
- A Million-Mile Storm Raging for Centuries – 6 Violent Weather Wonders in Our System - November 14, 2026
- Animals Flee Hours Before the Tremor – 7 Natural Warnings Before Disasters Strike - November 14, 2026
Florida lost its “can’t miss” status
Florida has spent two decades as the default answer to “where should I buy?” That’s no longer true in 2026. Among the 50 counties deemed most at risk, twelve were located in Florida, more than any other state. Condo values across the state have taken a real hit too, with prominent markets seeing sharp declines.
Housing analyst Nick Gerli says condo values have slipped by 9.9% in Florida over the past 12 months, with prominent markets including Palm Beach, Miami-Dade, and Tampa all seeing big declines. The culprit isn’t demand collapsing on its own. Ownership costs have surged since the 2021 Surfside collapse thanks to a sharp jump in insurance premiums and soaring HOA dues, with many insurance carriers withdrawing from the state’s condo market entirely as climate risks spike. Analysts now treat Florida less as a single market and more as a patchwork of very different risk profiles.
The insurance crisis rewrote the risk math entirely
This is the piece most casual buyers miss. It’s not just about whether home prices go up. It’s about whether you can even keep the house insured at a price you can afford.
Florida currently has the highest home insurance premiums in the nation, an average of $8,292, according to Insurify. And the risk of a claim actually paying out has become its own concern. One family in St. Petersburg, hit by two hurricanes within two weeks in 2024, discovered that despite having a home insurance policy limit of $713,000, their insurer offered to pay them only $2,279.41. Analysts have started treating insurance availability as a core underwriting variable, not an afterthought, and that alone has reshuffled which coastal markets still qualify as “safe.”
California’s most infamous bubbles quietly deflated
Here’s the twist nobody saw coming. The cities that spent a decade as poster children for housing bubbles are now being flagged as undervalued. For years, cities like San Francisco, San Jose, and Los Angeles were synonymous with extreme overvaluation, but today, after a necessary period of price correction, these markets have officially slipped into undervalued territory.
What makes this notable is the timing. This shift is happening just as the AI boom begins to create massive regional job growth and wealth. Analysts who once warned buyers away from the Bay Area are now pointing to it as an example of how a market can correct enough to become a reasonable entry point again, provided the local economy holds up.
Austin and the Texas frenzy markets came back to earth
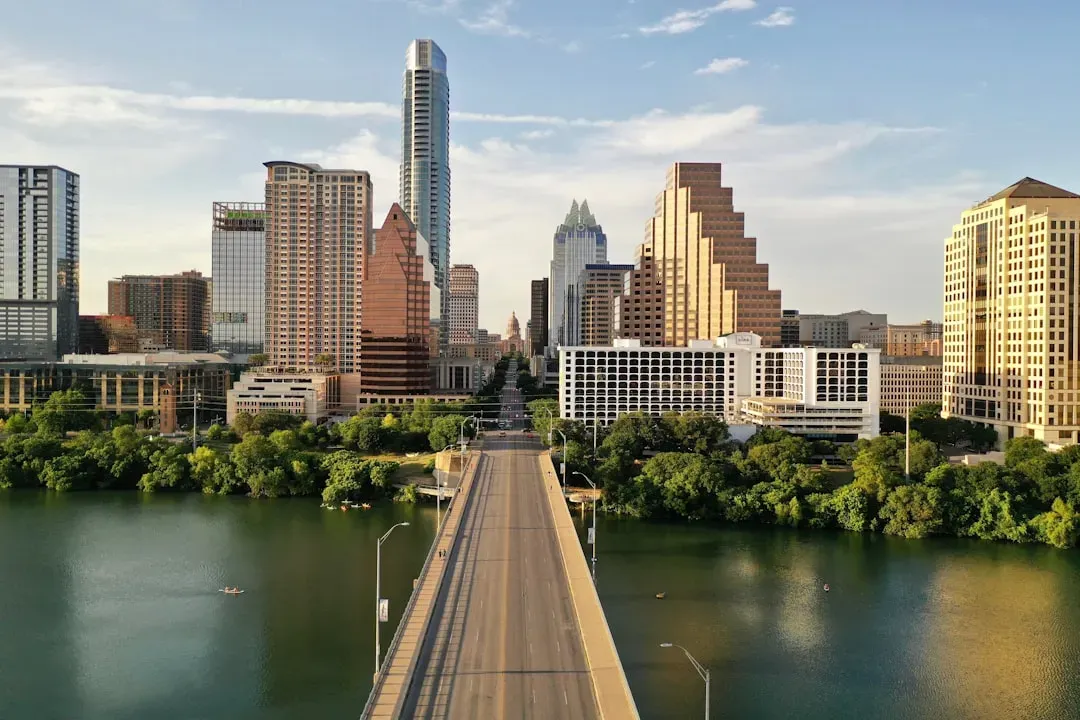
Texas was the other big pandemic-era darling, and Austin was its flagship. The scale of the correction there has been striking enough to change how risk models treat the whole region. Back in Q2 2022, Austin, TX metro was 65.4% “overvalued” according to Moody’s, but since then Austin has undergone a material home price correction, and as of Q2 2026 is now just 14.0% “overvalued.”
That’s not a crash, but it is a serious deflation of froth. Analysts describe it as a market working through excess rather than collapsing, which is a meaningfully different risk category. It also explains why some 2026 rankings that used to lump all of Texas together now separate the frothy former boomtowns from steadier metros like San Antonio or El Paso.
The Midwest and Northeast became the new safe havens
If there’s a single storyline running through this year’s risk reports, it’s the quiet rise of regions nobody was excited about a few years ago. Among the 50 counties identified as least at risk, nine were located in Tennessee, while Virginia and Wisconsin each accounted for five, and Michigan had four. Analysts point to constrained new construction as the underlying reason these markets are behaving so differently.
While these markets were not necessarily more affordable than others nationwide, they stood out for having some of the lowest unemployment rates, the lowest levels of foreclosure activity, and relatively small shares of underwater mortgages. Price data backs this up on a bigger scale too, since the current resilience of the Midwest and Northeast, led by states like New Jersey at 5.93 percent growth and Illinois at 4.83 percent, has provided a vital buffer for the national market. A region that spent years being described as slow and unglamorous is now being described as boring in the best possible sense.
Overvaluation is easing nationally, but unevenly
Zoom out to the national picture, and the numbers tell a story of gradual normalization rather than crisis. Roughly 70% of the nation’s top 100 metropolitan areas are still classified as overvalued, an improvement from 83% at this time last year. That’s real progress, even if it doesn’t feel dramatic on the ground.
The flip side is that not every market is correcting at the same pace. Year-over-year price growth continues its downward trend, slowing to just 0.5% in February 2026, while 13 states are now recording negative home price appreciation with Washington, D.C. and South Dakota topping the list with a 3% year-over-year decline. Analysts describe this as a rebalancing rather than a downturn, but it’s a rebalancing with clear winners and losers by geography.
Forecasters are split on how the second half of the year plays out
Even among professional forecasters, there isn’t total agreement on what comes next, which is itself telling. The Mortgage Bankers Association expects national prices could dip modestly in the back half of 2026 before growth resumes in late 2027, with some overbuilt Sun Belt metros already softening while supply-constrained markets keep climbing. The framing has shifted from asking whether a crash is coming to something more granular.
The better question analysts are now asking is which markets are softening and which are holding, since that’s the one that actually pays off for buyers and investors. On the ground, this shows up in supply numbers too. HouseCanary’s forecast splits the map clearly, with Syracuse projected at 4.2% growth and Chicago at 3.5%, while 77 of 387 metros, led by Florida, carry negative 12-month forecasts.
A crash still isn’t the consensus view, but affordability is the real problem
It’s worth separating two very different conversations that often get blended together. One is about whether prices will collapse. The other is about whether ordinary buyers can afford to enter the market at all, and most analysts agree the second problem is far more pressing right now.
Most experts agree that a housing market crash in 2026 is unlikely, as many homeowners have built up significant home equity and housing stock is low, and the issue is primarily an affordability crisis driven by high interest rates and inflated home values. Meanwhile, sentiment on the ground doesn’t always match the data. Despite 58% of Gen Z wanting a housing market crash, experts don’t foresee one in 2026, and if anything they see a greater sense of normalcy following multiple years of twists and turns.
Florida’s reform push is trying to change the narrative
It would be misleading to suggest Florida’s story is purely one of decline, since state officials are actively trying to reverse the insurance spiral that’s driving buyers away. Recent legislative reforms and increased insurer competition are beginning to stabilize the market, which could lead to lower premiums and improved insurance availability in 2026. Whether that materializes fast enough to change buyer psychology is a separate question entirely.
Some analysts are already distinguishing between Florida’s riskiest pockets and its more resilient ones. Investor entry is being framed as selective, with Miami luxury and Jacksonville single-family offering the best risk-adjusted profiles, while SW Florida condos and STR-heavy markets are best avoided until months of supply normalize and special assessment exposure becomes quantifiable. That kind of granularity, treating a single state as a dozen different micro-markets, is exactly the shift that’s defining how analysts approach risk in 2026.
What this means for buyers weighing their next move