
- Rain Shadows: Why One Side of a Mountain Range Can Be Lush and the Other Dry - October 13, 2026
- What Atmospheric Rivers Are and How They Bring Flooding to the US West Coast - October 13, 2026
- White Roofs, Shade Trees and Cool Pavement: 6 Ways Cities Are Cooling Their Streets - October 12, 2026
The policy does not simply transfer to you
A common assumption is that inheriting a house means inheriting the insurance that came with it, but that is not how most carriers operate. When you inherit a home, it is reasonable to assume that you also inherit the insurance coverage that protects it, but simply paying the insurance payment does not guarantee that you are insured. The policy is tied to the person named on it, not to the address.
When the named insured on a policy dies, the policy typically transfers to the estate, meaning the executor or administrator of the estate becomes responsible for maintaining coverage. That distinction matters because it puts the burden on whoever is handling the estate to actively manage the account, rather than letting it run on autopilot.
Notify the insurer quickly, before anything happens
Most companies build in a grace period, but it is shorter than people expect. You typically have around 30 days to alert the home insurance company that the policyholder died, otherwise the policy will likely get canceled. That window can pass quickly during a period already filled with funeral arrangements and paperwork.
Delays carry real consequences beyond a canceled policy. Reaching out to the insurer as soon as possible, ideally within 30 days of the homeowner’s passing, matters because delays could result in cancellation of the policy or denial of future claims. If a storm damages the roof before that call gets made, an insurer may later argue it never had proper notice of the change in ownership status.
Vacancy clauses can quietly gut your coverage
An empty house behaves differently than an occupied one, at least in the eyes of an insurance contract. Most standard homeowners insurance policies contain a vacancy clause, typically stating that if a property remains unoccupied for a continuous period, often 30 or 60 days, certain perils are no longer covered. That clause can strip away exactly the kind of protection you’d want during a hurricane season or a harsh winter.
Checking on the house from time to time does not necessarily satisfy the requirement either. After a deceased homeowner passes away, the original policy may offer limited protection, and this rule applies even if the estate executor occasionally checks on the vacant property. Insurers are looking at continuous occupancy, not periodic visits.
Weather damage is one of the biggest risks to an empty house
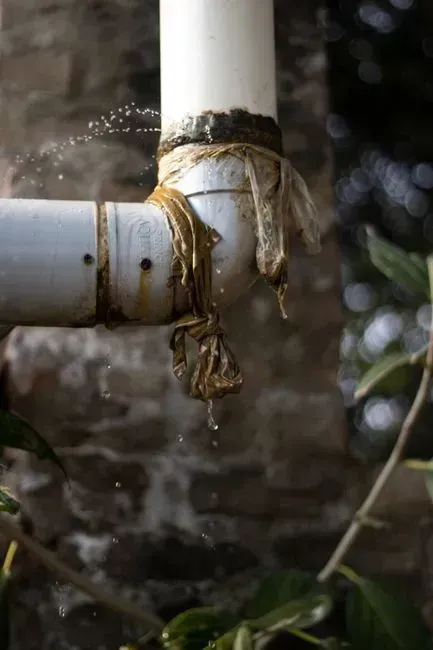
Storms don’t wait for probate to finish, and an unoccupied home is far more vulnerable when one hits. Water damage is one of the most common and expensive issues in unoccupied homes, with repairing damage from a burst pipe costing $10,000 to $70,000 or more depending on how long the issue goes unnoticed, since leaks can continue for extended periods before detection in vacant homes. A pipe that freezes and bursts during a cold snap might go unnoticed for weeks if no one is checking regularly.
Fire risk climbs too, oddly enough, in homes nobody is watching. A small electrical issue can smolder and spread, engulfing the entire structure before it’s found. Combine that with wind, hail, or a fallen tree limb, and an inherited home left unattended for even a season faces a wide range of exposures a lived-in house would not.
Vacant versus unoccupied is a real distinction
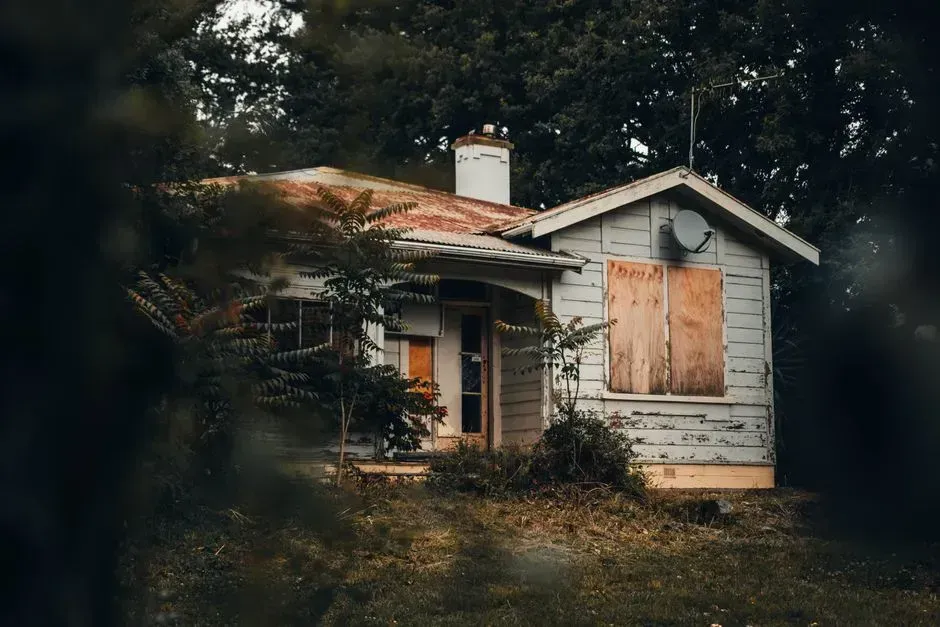
Insurers draw a technical line between two terms that sound similar but affect coverage differently. A “vacant” property generally means no occupants and no furnishings, while an “unoccupied” property is furnished, but no one is currently living there. If your parent’s furniture, dishes, and personal items are still inside, the home may qualify as unoccupied rather than vacant.
That classification can change both the cost and the type of policy required. An inherited home that still has furniture and personal belongings inside may qualify as unoccupied rather than vacant, which can affect the type of policy required and the cost. It is worth asking your carrier directly which category the home falls into, since the answer isn’t always obvious from the outside.
Vacant home insurance exists, but it comes at a price
Once a standard policy stops applying, a specialty vacant home policy becomes the fallback option. The cost of vacant home insurance is meaningfully higher than a standard policy, typically 25% to 50% more than what your parent was paying, according to Rocket Mortgage’s analysis of vacant home insurance costs, and many insurers limit coverage periods to 3, 6, or 12 months. Some sources put the increase even higher depending on the carrier and location.
Coverage under these policies also tends to be narrower than what a standard policy offers. Vacant property policies often limit coverage to specific named perils, such as fire, vandalism, and certain weather events, rather than the broader open peril coverage of a standard homeowner policy, and some insurers won’t write vacant policies at all, which may force heirs to use specialty carriers. It’s a stopgap measure, not something meant to last for years.
Liability exposure doesn’t disappear just because no one lives there
An empty house can still generate a lawsuit, which surprises a lot of people managing an estate for the first time. Liability protection is designed to protect you financially if someone is injured on your property and files a claim against you, and during probate, this protection extends to the estate and the estate executor, since if an individual, even a trespasser, is injured on the property, they could file a liability claim. A neighbor’s kid climbing a fence, or a contractor twisting an ankle on an uneven walkway, is enough to trigger a claim.
Without insurance backing that risk, the money to cover a judgment comes straight out of the inheritance. Without adequate insurance, the estate’s assets could be used to pay for legal fees and damages, which would reduce the inheritance intended for the beneficiary of property. Maintaining at least basic liability coverage during the transition period protects everyone who stands to inherit, not just the house itself.
Probate timing complicates everything
The legal process of settling an estate can stretch on far longer than families expect, and insurance has to keep pace with it. When a home goes into probate, it can take months or even years for the home to be officially inherited, or the court may rule that the heirs or executor must sell the home. That extended timeline means a temporary policy may need to be renewed more than once before the property changes hands for good.
There’s also a common misconception that you need to legally own a home before you can insure it, and that isn’t always true. It may be possible to insure a property that’s not in your name if you show an insurable interest in the property, meaning you have a good and logical purpose of protecting the home from loss. Executors and heirs alike should ask their agent about this option rather than assuming the house is stuck in limbo.
Mortgages add another layer of urgency
If the inherited home still carries a mortgage, insurance becomes a lender requirement, not just a personal choice. If you have a mortgage on the vacant property, your lender will require you to maintain insurance coverage to protect their financial interest. Skipping this step invites the lender to step in on its own terms.
When coverage lapses and no one corrects it in time, the servicer often takes matters into its own hands. If the inherited property has a mortgage and the insurance lapses, the servicer may obtain force-placed insurance after giving required notices. Force-placed insurance is typically expensive and offers far less protection than a policy the heirs choose themselves, so it’s worth avoiding through proactive communication with the loan servicer.
Practical steps that protect the estate right away
A handful of straightforward actions can prevent most of the problems described above. Premiums should continue to be paid from the estate’s funds throughout the probate or transfer period, and if the home is vacant, it’s more vulnerable to risks such as vandalism or damage, so the executor should ensure the property is locked, utilities remain on, and the home is regularly checked and maintained. These are small tasks compared to the cost of an uncovered claim.
It also helps to document the home’s condition early, in case a dispute over damage arises later. Photographing the home and taking inventory of valuables still inside, and asking about contents coverage, can matter if high-value items need separate treatment. Keeping every policy document, email, and phone call log in one place makes life much easier if a weather event does strike before the estate settles.
Final thoughts